Close Menu
  • Home
  • Crypto News
    • Bitcoin
    • NFT News
  • Metaverse
  • Defi
  • Blockchain
  • Regulations
  • Trading

Subscribe to Updates

Get the latest creative news from FooBar about art, design and business.

What's Hot

Bitcoin ETF inflows: Fidelity leads $433M Friday

September 19, 2026

Massive Crypto Acquisition: Why S&P Global Is Buying Blockchain Security Giant OpenZeppelin

September 19, 2026

‘Golden Cross’ Trap: Why Bitcoin’s Rally to $81,280 Worries Analysts

September 19, 2026
Facebook X (Twitter) Instagram
CredBit.com
Button
  • Home
  • Crypto News
    • Bitcoin
    • NFT News
  • Metaverse
  • Defi
  • Blockchain
  • Regulations
  • Trading
CredBit.com
Home » Why Wall Street giants build tokenization money for institutions, not regular consumers
Blockchain

Why Wall Street giants build tokenization money for institutions, not regular consumers

September 19, 20262 Mins Read
Facebook Twitter WhatsApp Pinterest Telegram LinkedIn Tumblr Email Reddit VKontakte
Why Wall Street giants build tokenization money for institutions, not regular consumers
Share
Facebook Twitter LinkedIn Pinterest Telegram Email

Treasury desks at major institutions are juggling three systems for the same job, said Jerald David, CEO of Lynq Network. A JPMorgan tokenized deposit for one client, a regulated stablecoin for another, a conventional correspondent account for a third. They move money on for the same reasons, but on different infrastructure.

“What clients can’t afford are separate pools of liquidity locked up on every network they access, because idle liquidity fragmented across five networks is five times the capital inefficiency of idle liquidity sitting in one place,” he said.

Unlike a stablecoin, a tokenized deposit remains a claim on the bank that issued it. It can bear interest, remain within the regulated banking system and potentially be programmed to settle against tokenized assets. The question is whether banks can deliver those benefits to consumers while maintaining privacy, compliance and control over who holds the deposit.

Interest-bearing deposits

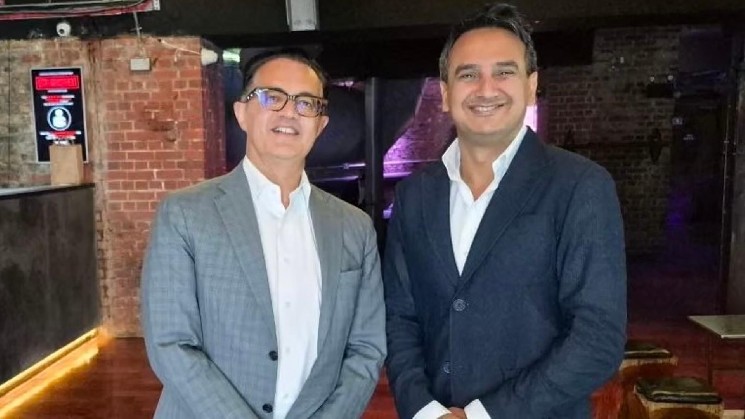
Bhandari said Monument, unlike stablecoin issuers, holds a banking licence that allows it to pay interest on deposits and plans to offer tokenized savings accounts that earn yield.

President of the Midnight Foundation Fahmi Syed said public blockchain infrastructure presents a separate challenge: banks cannot expose clients’ transaction data and commercial relationships.

“Once you create a private blockchain, how do you then speak to another private blockchain? You then have to use a bridge or some other mechanism, and at that point, you have data leakage.” JPMorgan and Citibank have recognized this themselves, Syed said.

Share. Facebook Twitter Pinterest LinkedIn Tumblr Email Reddit VKontakte Telegram WhatsApp

Related Posts

Massive Crypto Acquisition: Why S&P Global Is Buying Blockchain Security Giant OpenZeppelin

September 19, 2026

Bitcoin could reach 1 million dollars according to Kevin O’Leary

September 19, 2026

Vobile Group (SEHK:3738) Ties Up With Ant Blockchain On A Pricey AI Copyright Bet

September 18, 2026

Quantum Computing, AI, Digital Assets Expert to Conclude UW Blockchain Stampede

September 18, 2026

Blockchain Developers Are Racing to Protect Against the Quantum Threat. Here’s What It Means for Bitcoin and Ethereum Investors.

September 18, 2026

Hanwha Life enters Abu Dhabi through blockchain and tokenized assets

September 18, 2026
Leave A Reply Cancel Reply

Editors Picks

Bitcoin ETF inflows: Fidelity leads $433M Friday

September 19, 2026

Massive Crypto Acquisition: Why S&P Global Is Buying Blockchain Security Giant OpenZeppelin

September 19, 2026

‘Golden Cross’ Trap: Why Bitcoin’s Rally to $81,280 Worries Analysts

September 19, 2026

Solana Launches STOCKLANA, Emphasizing Continuous Trading

September 19, 2026
© 2026 - credbit.com - All Rights Reserved!
  • Contact Us
  • Disclaimer
  • Privacy Policy
  • Terms of Use
  • DMCA

Type above and press Enter to search. Press Esc to cancel.